
United Community Bank — United States (Georgia)
Overview of United Community Bank (Georgia): history, services, specialties, regulatory status, how to open accounts, and contact/website information.
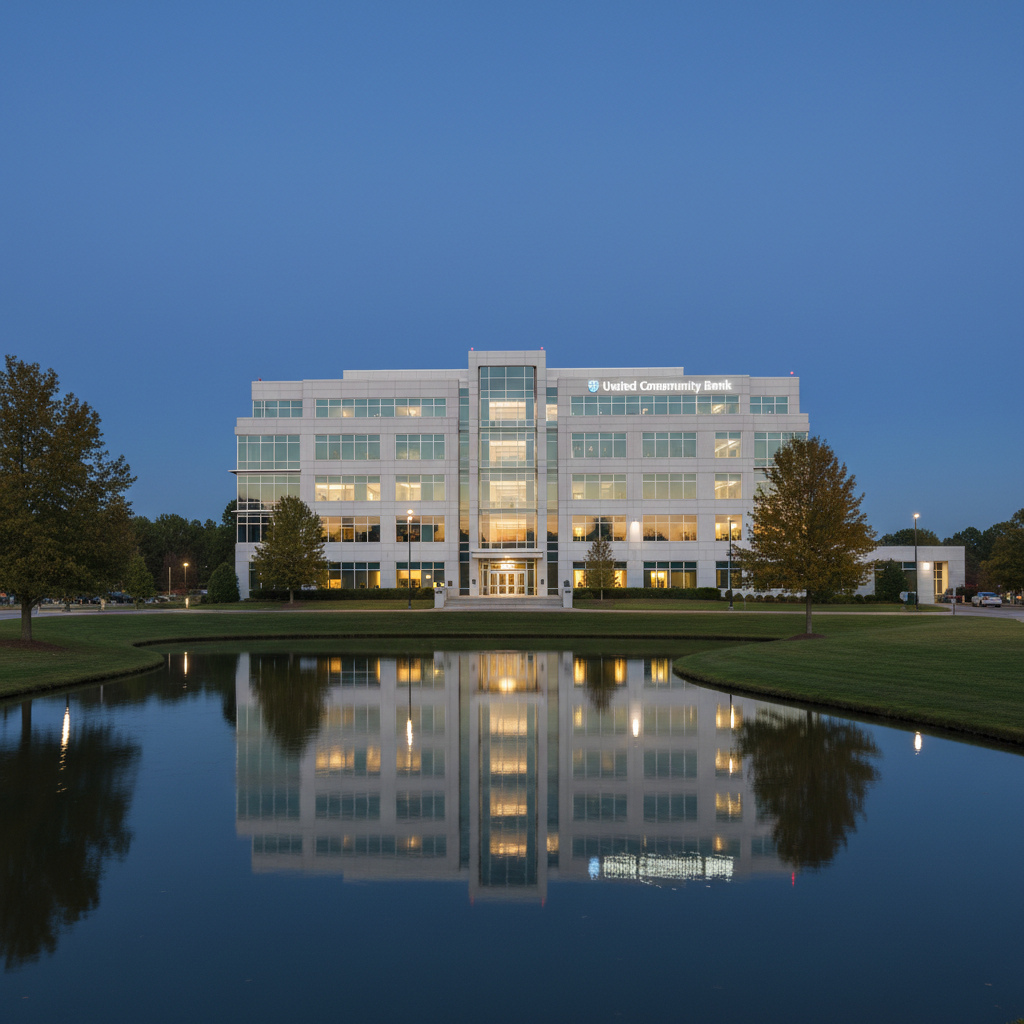
United Community Bank (Georgia): Overview
United Community Bank is a regional banking franchise operating in the southeastern United States with its corporate roots and primary operations in Georgia. Operating under the holding company United Community Banks, Inc., the bank has expanded from a local community institution into a multi-state regional bank offering a mix of retail, commercial and wealth-management services.
Brief history and founding
United Community Banks grew from small community banking origins in northern Georgia. Over several decades the company expanded its footprint through organic growth and a series of strategic acquisitions, broadening its geographic reach across the Southeast. Today the bank operates branches and business offices across multiple states while retaining a focus on relationship-driven community banking. The holding company for the bank is publicly traded (ticker: UCBI), reflecting its development from a single-community bank into a regional financial institution.
Type of bank
United Community Bank is a full-service regional bank that provides a blend of retail (consumer) banking, commercial banking, and wealth management services. It is principally a retail and commercial bank rather than an investment bank; its core activities include deposit-taking, consumer and business lending, mortgage origination and servicing, treasury and cash management, and advisory/wealth services.
Key services offered
United Community Bank's product suite typically includes:
- Personal banking: checking accounts, savings accounts, money market accounts, certificates of deposit (CDs), debit and debit-card services, and consumer online and mobile banking.
- Lending for consumers: home mortgages, home equity lines of credit (HELOCs), personal loans and auto loans where available.
- Business banking: business checking and savings, commercial lending (including commercial real estate, construction financing, and working capital loans), treasury management and merchant services.
- Specialty lending: Small Business Administration (SBA) lending, equipment loans and leasing options depending on local market capabilities.
- Wealth management and trust services: investment management, retirement planning, trust administration and private banking services delivered through affiliated wealth teams.
- Digital services: online and mobile banking platforms for account access, bill pay, remote deposit capture, and account alerts.
Service availability, specific account types, and product details may vary by market and branch.
Notable features and specializations
- Community and relationship focus: The bank emphasizes local decision-making and relationship banking, with many products and underwriting approaches tailored to small and middle-market businesses in its service areas.
- Commercial real estate and middle-market lending: United Community Bank has a strong presence in commercial real estate lending and middle-market commercial lending, reflecting its regional business customer base.
- Integrated wealth and trust services: The bank provides investment management and trust services alongside traditional banking, enabling bundled solutions for high-net-worth clients and business owners.
- Digital access combined with branch network: United Community Bank combines an expanding digital platform with a physical branch network to serve both consumer and business clients.
Regulatory status and deposit protection
United Community Bank operates as a banking subsidiary of United Community Banks, Inc., a bank holding company. As a depository institution in the United States, deposits at United Community Bank are insured by the Federal Deposit Insurance Corporation (FDIC) up to applicable limits (generally $250,000 per depositor, per insured bank, for each account ownership category). The bank is subject to federal and state banking regulations and oversight by appropriate regulators, including the FDIC and relevant state banking authorities; the holding company is subject to oversight as a bank holding company by the Federal Reserve.
For the most current regulatory disclosures, public filings, and supervisory information, consult the bank’s investor relations materials and federal agency databases.
How to open an account (general overview)
Opening an account at United Community Bank typically follows these general steps:
- Choose the account type: review checking, savings, business accounts or specialty accounts on the bank’s website to determine which product suits your needs.
- Gather required documentation: common requirements include a valid government-issued photo ID (driver’s license, passport), Social Security Number or Tax Identification Number, proof of address (utility bill or similar), and for businesses, Employer Identification Number (EIN) and formation documents plus list of authorized signers.
- Apply: applications can usually be completed in person at a branch or online via the bank’s digital platform where available.
- Make an initial deposit: minimum opening deposit amounts vary by account type; many accounts allow electronic transfers, debit card funding or in-branch deposits.
- Verify identity and sign disclosures: banks will complete identity verification, obtain signature cards or electronic consents, and provide account agreements and disclosures.
- Set up online/mobile banking and order checks or debit cards as needed.
Business accounts and certain loan products may require additional documentation and underwriting.
Contact information and website
- Official website: https://www.ucbi.com
- Customer and branch contact details: available through the bank’s website branch locator and contact pages. For account-specific questions or to open an account, use the website to find local branch phone numbers and hours or visit a branch in person.
For the latest product details, branch locations, and regulatory information, consult the bank’s website and public filings. If you need assistance locating a branch or contacting customer service, the website’s contact and branch-locator tools are the most reliable sources.
Disclaimer: This article is informational and based on publicly available descriptions of United Community Bank and its holding company. Product availability, branch presence, and corporate structure can change; verify details with the bank directly for the most current information.


